Figures current as of September 22, 2026. The market figures in this post age out in about 90 days, so re-check them after December 2026.
Every few weeks an investor sends me a Watertown two-family listing and asks whether the price works. This post runs the underwriting on a price a real building just traded at, with every number dated and sourced. If you already own a two-family here, the same math shows exactly what your building is worth to the buyers bidding this fall.
- A two-family at 38-40 Pequossette St. in Watertown, MA sold for $1,050,000 in the week ending September 13, 2026 (Watertown News).
- The average two-bedroom apartment in Watertown, MA rented for $2,800 a month as of August 29, 2026 (Zillow).
- Watertown's FY2026 residential tax rate is $12.20 per $1,000 of assessed value, and the owner-occupied residential exemption saves $3,961.52 a year (City of Watertown Assessing Department).
- The average 30-year fixed mortgage rate was 6.95 percent on September 17, 2026 (Freddie Mac Primary Mortgage Market Survey).
What a Watertown two-family grosses at today's rents
A Watertown two-family renting both units at the town's average two-bedroom rent grosses $5,600 a month, which is $67,200 a year. That rent figure isn't a guess: Zillow's Watertown rental data put the average two-bedroom at $2,800 a month as of August 29, 2026, down $12 from a year earlier. Flat, in other words, after three years of climbing.
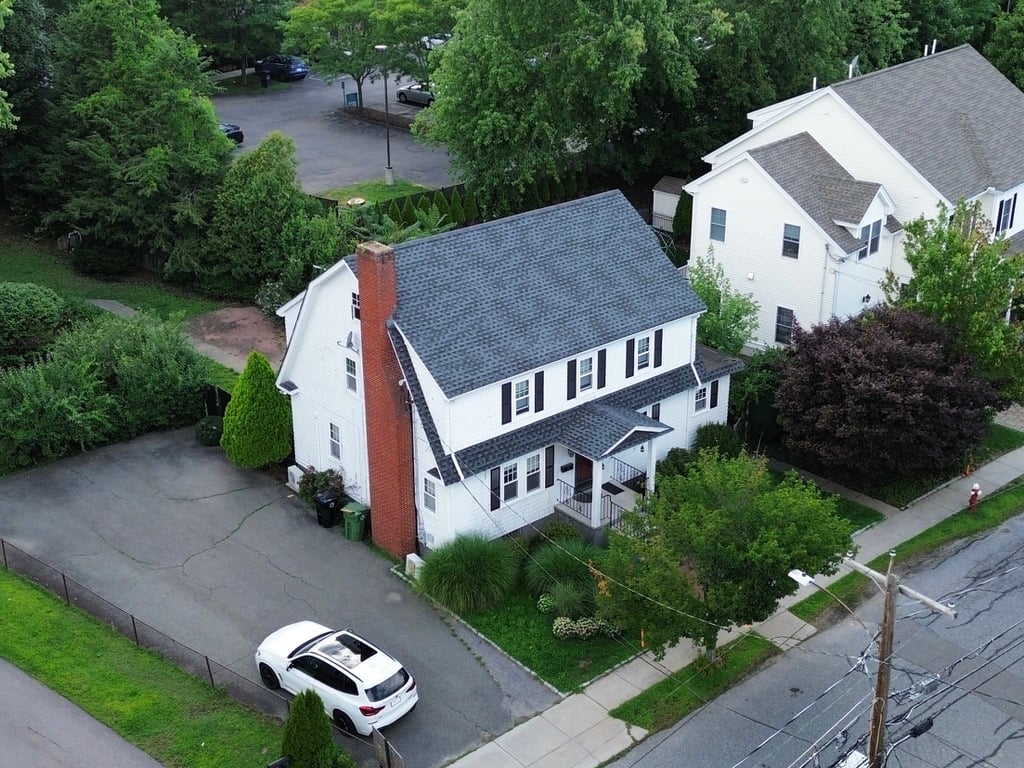
The building I am underwriting is real. Watertown News reported the sale of 38-40 Pequossette St., a 2,717 square foot two-family with four bedrooms and two baths across two units, for $1,050,000 in the week ending September 13, 2026. Two two-bedroom units at market rent is the honest income ceiling for a layout like that.
The ceiling is doing a lot of work in that sentence. Most two-families in Watertown don't change hands with both units at market. They come with a long-term tenant paying $2,300 or $2,400, and Massachusetts leases convey with the sale.
Our own September leasing runs in Watertown and Waltham put the cost of a vacant unit at $600 or more for every week it sits, so I underwrite the rents actually in place, never the rents the listing sheet imagines.
Where just under $30,000 a year goes before the mortgage
Before a dollar of debt service, I underwrite roughly $30,000 a year in operating costs on a $1,050,000 Watertown two-family. The biggest line is taxes. Watertown's FY2026 residential rate is $12.20 per $1,000 of assessed value, per the City of Watertown Assessing Department, so a building assessed at the full sale price carries a $12,810 annual bill. Assessments usually trail a fresh sale, so treat that as the ceiling rather than the bill.
The rest of my stack: $3,500 for insurance on a frame two-family, about $2,000 of landlord-paid water and sewer, two weeks of vacancy per unit at roughly $2,600, $5,000 in maintenance and capital reserves on a building this size, and 6 percent for management, about $4,000. I charge the management line even to self-managers, because your Saturdays are not free. Total, just under $30,000.
That leaves about $37,300 of net operating income, a 3.5 percent cap rate on the purchase price.
Now the debt: Freddie Mac's Primary Mortgage Market Survey had the 30-year fixed at 6.95 percent on September 17, 2026, and at that rate an 80 percent loan of $840,000 costs about $5,560 a month in principal and interest, roughly $66,700 a year. The building's entire NOI covers just over half of it. A pure rental underwrite doesn't carry this price, and everyone bidding knows it.
Why the owner-occupant usually outbids the investor
The marginal buyer of a Watertown two-family is usually someone who plans to live in one unit, because the city taxes that buyer less and the second unit pays a big piece of the mortgage. Watertown's residential exemption excludes $324,715 of assessed value on an owner-occupied home, worth $3,961.52 a year in FY2026. On the same $1,050,000 building, the investor pays about $12,810 in tax and the owner-occupant pays about $8,848.
The house-hacker's math never touches a cap rate. Put $210,000 down, borrow $840,000, and the $2,800 tenant unit covers roughly half the $5,560 monthly payment. That buyer compares their net cost against renting in Watertown and buying a condo, not against NOI. This is why two-families here clear at prices that make spreadsheet investors shake their heads, and why bidding against an owner-occupant on payment math with investor math usually ends one way.
What this means if you already own a Watertown two-family
If you have held a two-family here for twenty years, this market has quietly split your building's value in two, and which price you get depends on the rents in place the day you list.
An underwriting buyer at a 3.5 percent cap reads every dollar of missing rent harshly: units at $500 a month under market are $12,000 a year of missing income, roughly $340,000 of missing value on paper. Lenders count the leases that exist, not your opinion of market rent.
The owner-occupant buyer forgives soft rents more easily, but only on the unit they intend to occupy. A building with one unit delivered vacant and one at market is the strongest version of a Watertown two-family this fall, because it lets both buyer types bid their best number.
If your tenants are at 2021 rents on tenancies at will, the sequencing of renewals before a sale is a real decision with six figures attached, and it deserves more than a guess.
The third leg is the lot itself. Parts of Watertown sit inside the MBTA Communities 3A overlay, where zoning now allows more than what is standing, and a two-family on the right parcel carries land value a rental underwrite never sees. The MBTA 3A zoning hub explains the districts town by town, and our page on what 3A zoning does to property value covers how to tell whether your parcel is one of them.
The underwriting review to ask for before you offer or list
For buyers, PH Realty Group runs this exact underwriting on any specific listing before you offer: real in-place rents, the tax bill both ways, the expense stack, and what the lot adds, so you know your ceiling before the open house. For owners, ask for a rent analysis and valuation on your building, street by street, showing what it is worth with today's rents and what it would be worth re-tenanted.
Our Greater Boston multifamily investing page covers how we work with both. Ethan Piani-Hohmann, PH Realty Group, (781) 879-0863, [email protected].
Watertown two-family FAQ
Is a two-family in Watertown a good investment in 2026?
A Watertown two-family at September 2026 prices earns roughly a 3.5 percent cap rate at market rents, so it underperforms as a pure cash flow investment but has held value well as a live-in-one-unit purchase or a long-term equity hold.
What does a two-family cost in Watertown right now?
A 2,717 square foot two-family at 38-40 Pequossette St. in Watertown sold for $1,050,000 in the week ending September 13, 2026, per Watertown News.
What does a two-bedroom apartment rent for in Watertown?
The average two-bedroom apartment in Watertown, MA rented for $2,800 a month as of August 29, 2026, according to Zillow's rental market data, essentially flat year over year.
Do investors get Watertown's residential exemption?
No, Watertown's residential exemption applies only to owner-occupied homes, so in FY2026 an owner living in their two-family saves $3,961.52 a year in property tax that a non-resident investor owning the same building pays in full.
What is a realistic cap rate for a Watertown two-family?
At September 2026 prices and rents, a Watertown two-family bought at market and rented at market produces a cap rate in the range of 3 to 4 percent after realistic expenses.
Should I re-tenant my two-family to market rent before selling?
Often yes, because investment buyers price a two-family on the leases in place, and units rented $500 a month under market can read as roughly $340,000 of missing value at a 3.5 percent cap rate, but the sequencing depends on your tenancies and deserves a building-specific plan.
If you are weighing a two-family purchase or wondering what the one you own is worth now, PH Realty Group underwrites these buildings every week and will give you the real number before the market gives you its opinion.